All Categories
Featured

The Complete Guide on 2026 Medicare Options
You might not require a life insurance coverage policy after you've paid off your financial obligations and saved for your huge monetary goals, like retirement and your kid's college education. In these situations, a term life insurance coverage policy with a different retirement fund and other cost savings cars might offer what you need, and at a lower cost tag. As soon as you have a couple of quotes, you should: Compare coverage limitations, approximated month-to-month payments and administrative or management fees that come with each policy.
These are complex policies that might need some oversight, so it is necessary to deal with a monetary coordinator or another accredited expert before choosing one. You may also compare IUL policies against other kinds of life insurance coverage to see what works best for your circumstance. Depending upon who you ask, indexed universal life (IUL) insurance coverage is either an effective wealth-building technique or an overly complex insurance item that guarantees more than it provides. However, the fact might lie somewhere in the middle . An IUL is very first and primary a life insurance coverage policy. Like other long-term life insurance products, it can provide long-lasting coverage and build cash value in time. Rather of earning a set rate of interest, it's tied to the performance of a stock market index, such as the S&P 500. Here's how indexed universal life insurance works, who it may be a good fit for, and what to know before buying a policy. Indexed universal life insurance coverage is a type of irreversible life insurance that combines a survivor benefit with a cash worth account. Unlike whole life insurance, which credits your cash worth at a fixed interest rate, an IUL ties your money worth growth to the performance of a market index, such as the S&P 500, the Dow Jones Industrial Average, or the Nasdaq Composite(thus the "indexed"part of the name). Every premium payment you produce a UIL policy is generally split 3 ways: Just like all money worth life insurance coverage, you may be able to borrow against your balance, withdraw funds, or even utilize it to assist cover future premiums. Instead, the insurer uses the index as a standard to determine how much interest to credit to the money worth portion of your policy. If the index carries out well, your money worth may earn more interest. If the index has a bad year, your credited interest may be lower(sometimes even 0%), depending upon your policy's terms. If your policy credits the.
complete 10%, your cash worth could earn about $5,000 in interest before fees and policy charges. When you hear that an IUL's money worth is linked to the stock exchange, you may presume you'll make whatever the marketplace makes. But that's hardly ever how it works. A cap is the optimal interest your policy can earn throughout a crediting period. You can normally find your cap in your policy illustration or documents.
Expect your policy has a 10 %cap, and the market index gains 15%that year. Although the index increased by 15 %, your policy would only be credited 10 % before charges and other policy charges. Lots of IUL policies have a 0 %flooring, meaning you will not lose cash value merely since the underlying market index has an unfavorable year. For instance, if the index falls 18%, your credited interest might be 0%rather of -18%. That stated, a 0 %floor protects you from market losses, not from policy costs. A participation rate identifiesjust how much of the index's gain is credited to your policy. If your policy has an 80 %participation rate and the index increases 10%, you would get 8%interest (80%of the index's gain), assuming no cap restricts the return. If the participation rate is 100 %, you would earn the complete 10 %as long as it does not go beyond the cap. 2 policies tracking the exact same marketindex can produce really various results depending upon how these features are structured. Most indexed universal life policies let you select in between two kinds of death benefits: Your beneficiaries receive a fixed death advantage throughout the life of the policy. As your cash worth grows, it normally enters into that overall death benefit instead of being paid in addition to it.
Why Final Expense Insurance Protects Your Future
That versatility can be substantial if your income modifications from year to year, or you go through a huge life occasion (such as divorce or temporary work leave) and still wish to keep your policy in force. It also implies you'll need to pay closer attention to your policy over time.
Insurance in Lakewood CAThis table highlights the greatest distinctions: Both entire life insurance and indexed universal life supply you with permanent coverage that constructs money worth, but how that money worth grows is rather different. Entire life insurance coverage normally has actually ensured development at a fixed rate, while IUL has the capacity for greater returns because its cash value is tied to a market index.
Term life insurance coverage is typically the most cost effective and most convenient kind of life insurance coverage to get. It doesn't develop cash worth, but you get a guaranteed death benefit for a set duration of time, often at a portion of the expense of an IUL policy. You can believe of a variable universal life insurance coverage policy as one action above an IUL policy in terms of danger and benefit.
Insurance in Lakewood CAThis means you'll have greater development potential however also the possibility of investment losses. Like any financial item, indexed universal life insurance has advantages and trade-offs. If your main objective is just changing your earnings for your family, a term life insurance coverage policy is typically simpler and far less expensive.
Common expenses might consist of:, which usually increases as you age for managing the policy subtracted from your payments if you include features like long-lasting care or chronic health problem advantages if you cancel the policy throughout its early years Before you buy an indexed universal life policy, the insurance provider will generally provide an illustration showing how your policy could carry out gradually.

Latest Posts
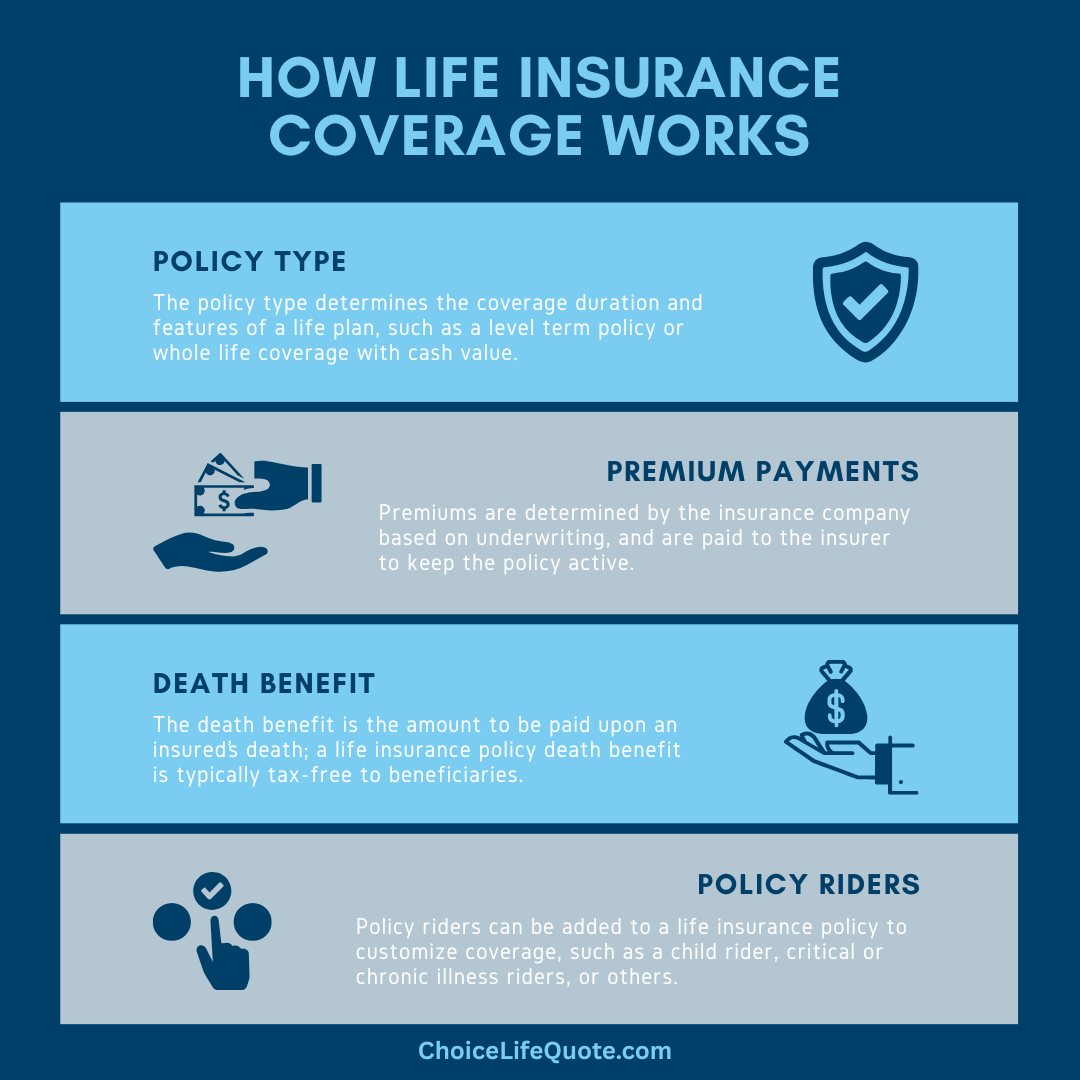
How Whole Life Insurance Functions

Comparing 2026 Medicare Supplement Plans in Huntington Beach
The Complete Guide on 2026 Medicare Options